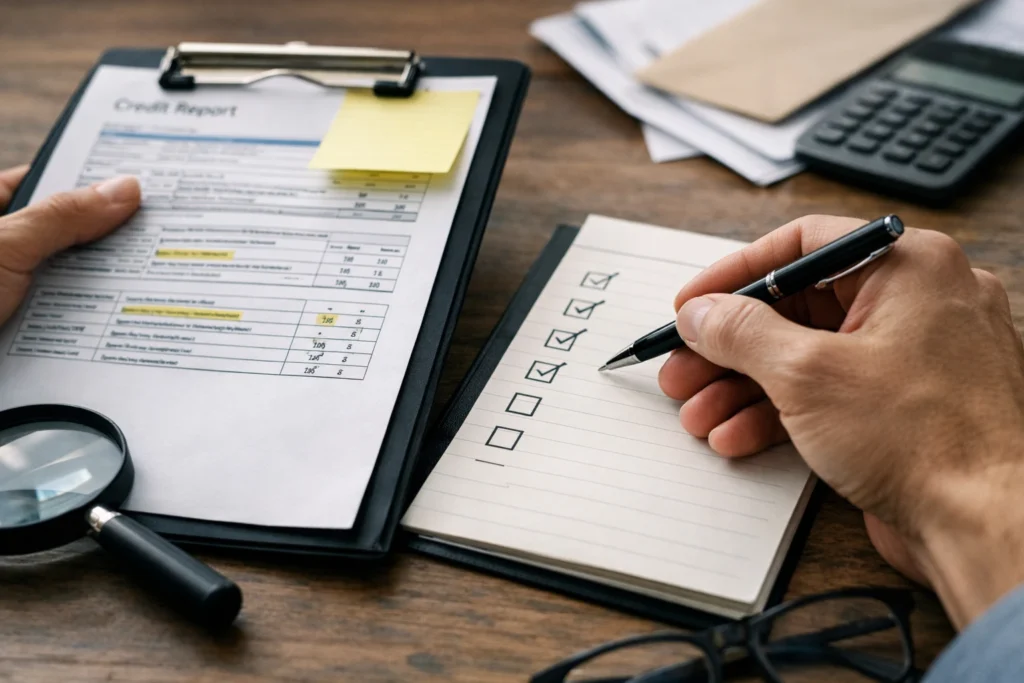
The How to Dispute Errors on Credit Report Checklist
At a kitchen table, a borrower circles a wrong late-payment mark on a printed credit report, lays out bank statements beside it, and starts a folder labeled “dispute.” The mistake looks small — one line, one date, one red mark — but it can hold up a mortgage preapproval, a rental application, or a credit card approval you need this month.
If you are trying to learn how to dispute errors on credit report, do not start with frustration. Start with paperwork. A dispute built from memory turns messy fast. A dispute built from the newest report, the right bureau, and a clean evidence packet gives you something much better: a record you can prove.
You also do not need a secret script or a paid shortcut. You can do every step yourself for free. Under the Fair Credit Reporting Act, credit bureaus generally have 30 days to investigate a dispute, with that window stretching to 45 days in specific situations. That timeline matters when you are fixing a false 30-day late before closing on a home in Dallas or trying to clear a mystery collection before signing a lease in Atlanta.
1) Start with the official dispute map for how to dispute errors on credit report
Pull the latest report you can verify
Watch This Helpful Video
To help you better understand how to dispute errors on credit report, we’ve included this informative video from Naam Wynn. It provides valuable insights and visual demonstrations that complement the written content.
Begin with the newest report you can confirm, not an old screenshot from six months ago. The FCRA gives you the right to free annual credit reports, and the official place to pull them is AnnualCreditReport.com. On top of that, Equifax says consumers can get free weekly credit reports and a free Equifax credit report and score through its consumer help options.
If you are on a tight deadline — a refinance, a VA loan, or a rental screening due Friday — the report date matters. Use the version that shows the current account status, current balance, and current reporting date.
Identify which bureau shows the error
Compare the same account across all three reports. The error may appear on Equifax and not on Experian. Or it may show up on one bureau with the wrong balance and on another with the wrong payment history. Write down the bureau name, account name, account number ending, date of the error, amount involved, and what you believe is wrong.
Be exact. “This account is wrong” is weak. “Auto loan ending 4821 shows 60 days late in May 2026, but my bank confirmation shows payment posted April 29, 2026” is specific enough to investigate.
Choose the official help page before you file
Use current, official sources first. USAGov maintains an official “Dispute credit report errors” page in its Money and credit section on a secure .gov site. Equifax has dispute help within its consumer services. Experian has a resource specifically titled “Check your credit report and file disputes.” Start there before you copy language from a forum, a video comment, or a “credit sweep” template.
| Official source | What it helps you do | What to confirm before moving on |
|---|---|---|
| USAGov | See the government’s dispute roadmap on a secure .gov site | Which bureau has the error and what kind of account it is |
| Equifax | Review Equifax information, dispute data, and recheck updates | Report date, disputed line item, and case number |
| Experian | Check your report and file disputes through its help resources | Whether the same issue appears there too |
Do not dispute from memory; start with the newest report in front of you.
2) Gather proof before you file
Collect statements, letters, and payment records
Build a simple evidence packet before you touch the dispute form. In most cases, that packet includes account statements, payment confirmations, collection letters, screenshots or copies of the reported error, and any email or letter from the lender or collector. If you paid by check, add an image of the cleared check. If you paid through your bank’s bill-pay system, include the payment confirmation page.
When a collector is involved, keep your timelines straight. The Fair Debt Collection Practices Act gives you a 30-day validation window after an initial collection notice to ask the collector to validate the debt. That is separate from a bureau dispute, but the records often overlap. If the collector reported the wrong balance or the wrong person, save every letter.
-
Account statement showing the correct balance or payment status
-
Bank record or confirmation number proving the payment date
-
Letter or email from the lender, servicer, or collector
-
Printed or saved copy of the credit report page with the error
Mark the exact line item, date, and amount
Circle the exact problem. Then label it. Note the date reported, the amount, and the status line you are disputing. If the issue is a duplicate collection, point to both entries. If the issue is a wrong balance, state the reported balance and the balance you believe is correct. If the issue is identity theft, note every account you do not recognize.
Specificity wins here. If a student loan shows a $0 balance on one report but $8,214 on another, say that. If a card from 2024 shows “charged off” even though the account belongs to someone with a similar name, say that. Clean facts travel farther than emotion.
Add identity-theft or military protections if needed
If identity theft is part of the story, handle protective steps at the same time you prepare the dispute. Equifax’s consumer help menu includes options for a security freeze and for requesting a fraud or active duty alert. It also points consumers toward help paths for identity theft and for preparing to make a large purchase.
If you are active duty, recently deployed, or managing a spouse’s paperwork during PCS season, do not leave those protections for later. If a thief opened the account, freezing your file or adding the right alert may matter just as much as disputing the tradeline itself.
If identity theft is involved, handle the freeze or fraud alert step at the same time you prepare the dispute.
3) Submit the dispute the simplest way you can document
Use online if you want speed and a paper trail
Online filing is usually the fastest route when the bureau lets you upload documents and gives you a confirmation screen. Equifax says consumers can handle disputes online, and its support language frames much of the process as self-service. That can work well when you have a clean PDF packet and you are ready to take screenshots of every step.
Save the final submission page. Save the case number. Save the email confirmation if one arrives. If your browser times out at 9:47 p.m., you want proof of what actually went through.
Use mail if you want copies you can keep
Mail is slower, but it can be cleaner. You control the packet. You control the order. You keep the exact copy you sent. If you choose mail, send copies rather than originals, list each disputed item clearly, and keep the mailing receipt with the packet.
This is also where a lot of people overpay for help they do not need. No law requires you to hire a credit repair company to write or mail a dispute. You can handle every repair step yourself. That is one reason you should be skeptical of anyone selling “exclusive” letters or promising to erase accurate negatives.
Use phone only if you record the reference number
Equifax also says consumers can get live help by phone and use mail-in forms for some services. Phone can be useful when you need clarification today, or when the online portal will not accept your upload. Still, a call leaves a thinner trail than a saved portal screen or a mailed packet.
If you use the phone, write down the date, time, representative name or ID if given, and the reference number. Then follow up by saving any written confirmation you receive.
| Method | Best for | What to save | Main downside |
|---|---|---|---|
| Online | Fast filing and easy document upload | Screenshots, confirmation email, case number | Portals can limit explanations or time out |
| Full packets and exact copies for your records | Letter copy, attachments, mailing receipt | Slower turnaround | |
| Phone | Quick clarification or access help | Reference number, call notes, follow-up email | Weakest paper trail if you do not document it |
Pick the filing method you can prove later, not just the one that feels fastest today.
4) Track the investigation and save every response
Save confirmation numbers and screenshots
Treat the dispute like a case file. Save upload receipts, letters, emails, status messages, and screenshots. I like a simple log with five columns: bureau, account, date filed, confirmation number, and next follow-up date. That log takes two minutes to build and can save hours later.
Once a bureau receives your dispute, the FCRA generally gives it 30 days to investigate. In some situations, that can stretch to 45 days. Put the deadline on your phone calendar the day you file. If you submitted on October 13, mark the 30-day point immediately.
Check whether the correction appears on the next report
Do not stop at a status update that says “completed.” Pull a fresh report and compare the actual tradeline. Equifax’s free weekly credit reports can help here because they give you a practical way to recheck without waiting months. Experian also ties its dispute guidance to checking your report and filing disputes, which tells you something simple but useful: the report itself is the thing to verify.
Look at the exact fields that were wrong before — payment history, balance, account status, dates, and remarks. If your report now shows the late mark removed but the balance still wrong, you are not done.
Note the date the bureau says it updated
Write down the outcome and the update date. Did the bureau delete the item, correct it, or verify it as accurate? Save the updated PDF or printout. If you need to show a lender that the file changed before underwriting, that document matters.
If the result says “verified as accurate” and your proof still says otherwise, the next step may be another dispute with clearer evidence or a direct dispute with the lender or collector that supplied the information. Keep the timeline intact.
A corrected report is not the finish line until you verify the change on a fresh report pull.
5) Catch the common misses
Do not stop after one bureau response
The biggest operational mistake is assuming one correction fixes every version of your file everywhere. It may not. One bureau’s correction does not always automatically update the others. If Equifax corrected the account, still check Experian and your third report. Mortgage lenders, landlords, and card issuers do not all pull the same bureau.
This matters a lot when timing is tight. A renter in Chicago may pass one screening service and fail another because only one report updated. A borrower chasing a 620 threshold for a specific loan program may find that one bureau moved and another did not.
Do not forget fraud, freeze, or active-duty protection
If the error came from identity theft, a bureau dispute alone may leave the door open for more damage. Equifax’s consumer services include a security freeze, a fraud alert, and an active duty alert. Use the protection that fits your situation. If someone opened a card in your name last week, stopping new misuse matters right now.
And if you are on active duty, do not assume your military status is “understood” by the system. Add the protection you need and keep your own records of when you requested it.
Do not skip military or identity-theft follow-up steps
Fast-fix myths burn a lot of time. Accurate negative information does not disappear because you mailed a template or bought a “sweep.” Under the FCRA, many negative items can remain for up to 7 years, and some bankruptcies can stay for up to 10 years. Disputes are for inaccurate, incomplete, or unverifiable information — not for true negatives you simply do not like.
If you are dealing with identity theft, military orders, or a disputed collection, keep every follow-up letter. If a collector is involved, keep your validation request and their response. If a service promises a brand-new profile, a CPN, or guaranteed deletion of truthful data, walk away.
The biggest miss is assuming one fix solves every version of the file everywhere.
6) Finish with a monitoring plan and next step
Set a reminder to pull the next report
Set the next review date before you put the paperwork away. If your dispute is time-sensitive, use a weekly reminder. If the issue is less urgent, set a 30-day and 60-day check. Equifax’s free weekly credit reports make frequent rechecks realistic for many consumers, especially when you are tracking a recent correction.
A simple routine works. First Monday of the month. After payday. The day your mortgage broker asked for updated documentation. Pick one.
Escalate if the item comes back or stays wrong
If the item remains wrong, comes back after deletion, or changes only halfway, reopen the file with stronger proof. You may need to dispute again with the bureau, contact the lender or collector that supplied the information, or gather an additional letter that settles the factual point. USAGov remains a solid official starting point for dispute-related credit report issues.
Keep your adverse action notices too. If a lender denied you on November 2 because of a report error you are disputing, that timeline may matter later when you explain what changed.
Repeat the process for each disputed account
Do not cram three unrelated disputes into one vague complaint. Run the same process for each account: identify the exact error, attach the matching proof, file through an official channel, log the dates, and recheck the report. A false medical collection, a duplicate charge-off, and a wrongly reported late student-loan payment are three separate problems.
That sounds repetitive because it is. Repetition is what makes the process reliable.
Set your next review date before you put the paperwork away.
This process turns how to dispute errors on credit report into a repeatable routine: document the mistake, file through an official channel, verify the fix, then keep watching.
You do not need magic words or a paid shortcut. You need current reports, organized proof, and the discipline to recheck what changed.
When you pull your next report, what is the first account you need to verify line by line?
Build Clarity With Credit Score Repair
Score basics, range explanations, dispute guidance, rebuilding ideas, and theft-protection steps help Americans handle report errors, debt setbacks, renting pressure, mortgage prep, or veteran concerns.
This article is for educational purposes only and is not legal, tax, credit, or financial advice. Credit laws and reporting practices can change, and the right next step may depend on your facts, service status, identity-theft risk, and the source of the reported information. Review current guidance from official government and bureau sources, and consider speaking with a qualified attorney or financial professional when you need advice tailored to your situation.